After a significant storm event in Jacksonville, homeowners expect the insurance process to move quickly. It rarely does. From the moment you open a claim to the day the depreciation holdback clears your account, expect 10-12 weeks under normal conditions — and longer if the storm hit a wide swath of Duval County and triggered a post-storm surge in adjuster demand.
What follows is a realistic week-by-week breakdown based on what JK Prestige's roofing crews and clients have observed across dozens of storm-damage claim cycles in Northeast Florida. Not the insurance company's version. The actual version.
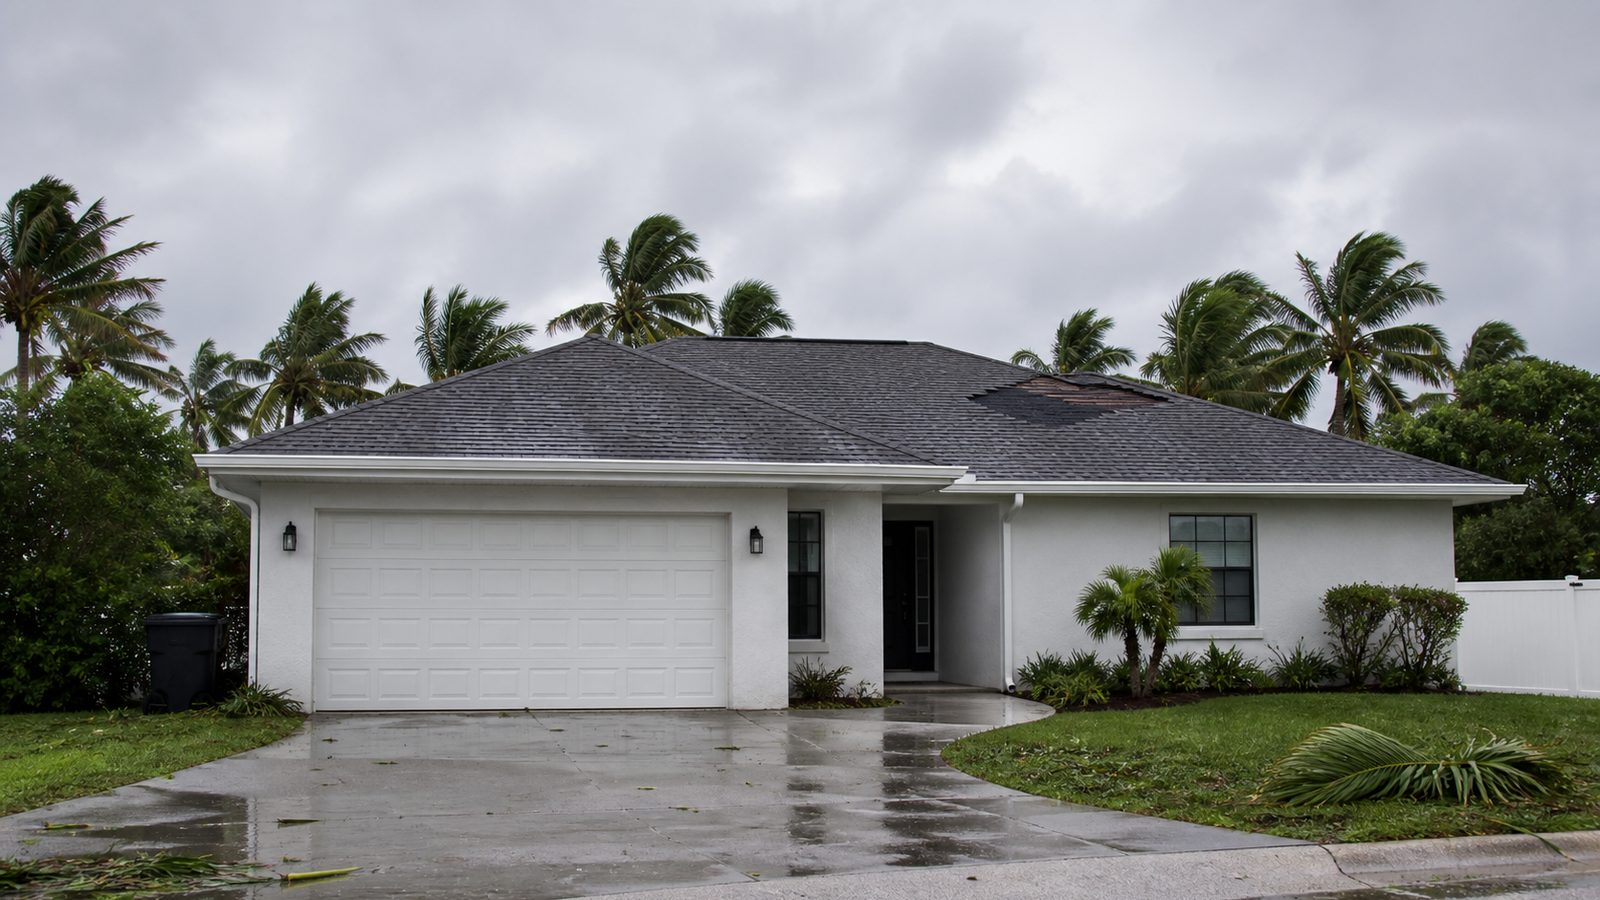
Week 1: Document the Damage, Open the Claim, and Secure the Roof
The clock starts the moment the storm passes. Do not wait for the adjuster before you act.
Document first. Walk the exterior and photograph every visible impact point — hail strikes on vents and gutters, torn or missing shingles, debris impact marks on ridge caps, damaged soffits and fascia. Date-stamp every photo. Upload them to cloud storage before you file.
Open the claim the same day. Call your insurer and open a claim immediately. Every day of delay is a day they can argue the damage is unrelated to the event. Get the claim number in writing.
Request emergency tarp if there is active water intrusion. JK Prestige deploys emergency tarps 24 hours a day, 7 days a week. If rain is getting inside, a tarp is not optional — it is mitigation you are required to perform under most Florida homeowner policies. Document the tarp installation with photos and keep all receipts. Emergency tarping costs are typically reimbursable as part of the claim.
Weeks 2-3: The Adjuster Visit — and Why It May Take Longer
After a widespread storm event, insurance adjusters in Jacksonville get overbooked fast. A single significant hurricane or tropical storm can create a backlog that stretches the adjuster visit to 3-4 weeks from claim opening rather than 1-2.
What happens at the adjuster visit. The adjuster walks the roof, catalogs visible damage, and photographs the same things you already photographed. They are working for the insurance company — their estimate is a starting point, not the final word.
Request to be present during the inspection. You are entitled to be there. Have your own documentation ready. If you've already had JK Prestige perform a free 24-point roof inspection with a written report, bring that report to the adjuster visit. A documented inspection from a licensed GC carries weight.
Know the difference between an independent adjuster and a staff adjuster. Staff adjusters work directly for your carrier. Independent adjusters are contracted out. After a major storm, carriers frequently deploy independent adjusters who may be unfamiliar with local material costs and labor rates in Jacksonville.
Weeks 3-4: The Adjuster Issues an Estimate — Often Incomplete
The adjuster estimate arrives. It will frequently undervalue the scope of work.
Common gaps in adjuster estimates for Jacksonville homes:
- Code upgrade items. Florida building codes require certain upgrades when a roof is replaced — ice and water shield at eaves, drip edge to current spec, ventilation to code. Adjusters often exclude these as "betterments."
- Decking replacement. If underlying decking is damaged, it needs to come out. Adjusters will often note "inspect decking at time of replacement" rather than authorize it upfront.
- Full replacement vs. repair. If more than a threshold percentage of shingles are damaged, replacement is appropriate. Adjusters sometimes push repair when replacement is the correct call.
- Matching shingles. If the damaged field matches shingles no longer manufactured, Florida's matching statute (Section 626.9744) may require a full replacement to achieve a uniform appearance. This is frequently left out of initial estimates.
Weeks 4-6: Supplement Negotiations
This is where most of the timeline variance lives.
A supplement is an additional payment request submitted to the insurer when the initial estimate does not cover the full scope of repairs. Supplements are normal, expected, and often necessary. Carriers know this. It does not mean the claim is in dispute — it means the initial estimate was incomplete.
JK Prestige handles supplement documentation directly. We line-item every missing scope item with Xactimate pricing references, code citations, and photo documentation. The carrier's desk adjuster reviews it, may request additional photos or documentation, and issues a revised estimate.
If negotiations stall, a public adjuster can be engaged. Public adjusters work for you, not the carrier. They typically charge 10-15% of the final claim payout. Engaging a public adjuster adds 2-4 weeks to the process minimum — but on large or disputed claims, the increase in payout often more than offsets the fee.
Weeks 6-8: Material Ordered and Delivered
Once the scope is settled and the initial Actual Cash Value (ACV) payment is issued, materials can be ordered.
GAF and CertainTeed lead times matter here. Under normal conditions, shingles ship in 1-2 weeks. After a widespread storm event — think a hurricane that affects multiple Florida counties — distributors sell down inventory fast. Lead times of 3-5 weeks for specific shingle profiles and colors are not unusual post-storm.
JK Prestige carries standing inventory relationships with our GAF Master Elite and CertainTeed Select certifications. We pre-order when possible on large storm events. If you are hiring a roofing contractor without manufacturer relationships, add time to this phase.
Other materials with potential lead times post-storm:
- Synthetic underlayment (demand spikes region-wide after events)
- Custom ridge cap for metal roof systems
- Specialty flashing for tile or slate transitions
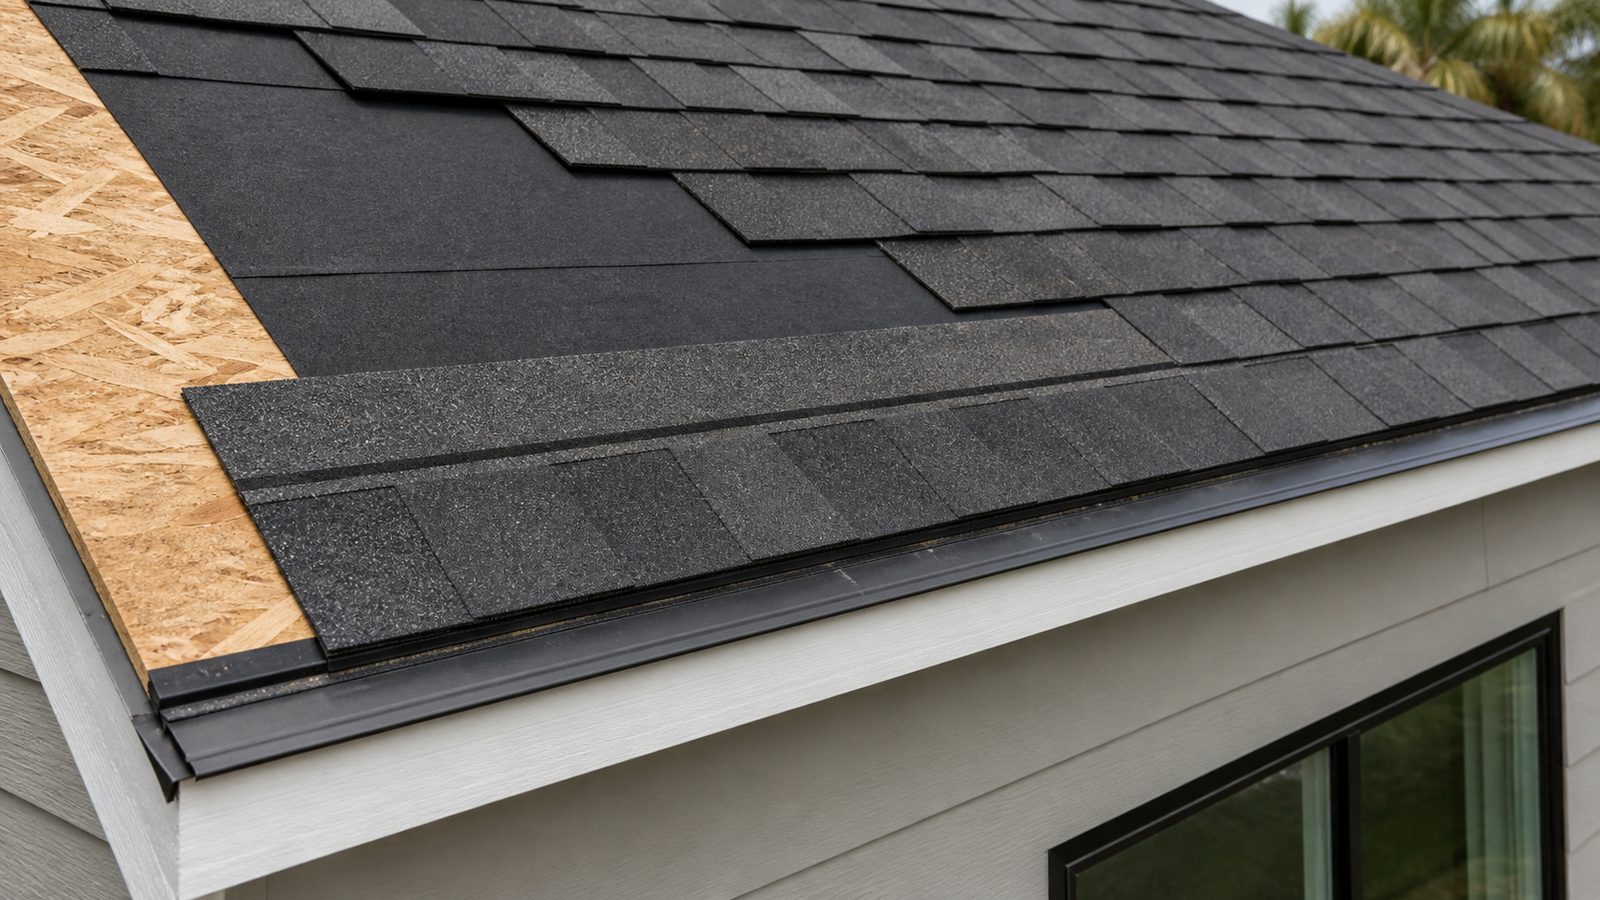
Weeks 8-10: Installation
Installation on a standard Jacksonville residential roof — 20-30 squares — typically runs 2-4 days with a full crew. JK Prestige self-performs roofing with our own crews, not brokered labor, which means we control the schedule. We are not waiting on a sub to become available.
The installation sequence:
- Full tear-off of damaged shingles and underlayment
- Decking inspection and replacement of any compromised boards (documented and photographed for the claim)
- Drip edge and ice/water shield at eaves per Florida code
- Synthetic underlayment installation
- Shingle installation per manufacturer specifications
- Ridge cap, step flashing, and penetration sealing
- Final inspection and cleanup
Post-installation, we provide a completion report with photos of every phase — not just the finished surface, but the substrate. This documentation is required to release the depreciation holdback.
Weeks 10-12: Final Payment — Releasing the Depreciation Holdback
Most insurance policies pay out on an Actual Cash Value (ACV) basis first, then release the depreciation holdback — called the Replacement Cost Value (RCV) supplement — after you submit proof of completion.
What proof of completion requires:
- Contractor's signed certificate of completion
- Final invoice showing the amount paid
- Photographs of the completed installation
Submit these to your adjuster immediately after installation. The carrier then processes the RCV release, which typically takes 10-14 business days.
The holdback amount varies by age and condition of the original roof. On a 12-year-old shingle roof, the depreciation holdback can represent 30-40% of total claim value. Do not skip this step.
What Extends the Timeline
Claim disputes. If the carrier denies a portion of the claim and you disagree, you enter a dispute process. Appraisal (binding arbitration between two appraisers and an umpire) is the most common resolution mechanism under Florida law. Add 4-8 weeks.
Public adjuster involvement. Adds time but frequently increases payouts. Worth evaluating on claims over $15,000 where there is meaningful scope disagreement.
Supplement complexity. Multiple iterations of supplement submission and review can add 2-4 weeks per round.
Material shortages after widespread events. If a major storm affects 10+ Florida counties simultaneously, every contractor in the region is ordering materials at the same time. Distributor stock depletes. Lead times extend.
Permit delays. Duval County requires a permit for roof replacement. Post-storm surges create longer review queues. Plan 2-3 weeks for permit issuance after a major event.
What JK Prestige Handles for You
JK Prestige's roofing division functions as your liaison through every phase of this process:
- Free 24-point roof inspection with written report before the adjuster visits
- Emergency tarp deployment, documented and billed to the claim
- Adjuster meeting attendance and scope documentation
- Supplement preparation and submission
- Permit filing and inspection coordination
- Proof of completion package submitted directly to your adjuster
A JK principal's number is in your contract from day one. Not a call center. Not a coordinator who wasn't at the adjuster meeting. The person who signed your contract knows every line item and handles every call.
See how we approach the full roofing process and warranty coverage.
Book your free 24-point roof inspection. we issue the written report before your adjuster shows up: jkprestigeconstruction.com/#/contact or call (904) 944-0278. A principal answers.
No call center. No coordinator. A JK principal reviews every inquiry and replies with a real number, not a range, not a follow-up form.
Request Free Estimate →